
PT Medco Energi Internasional Tbk is entering the final months of 2026 with stronger earnings and higher oil and gas production after first-half net income surged to about $275.3 million. The performance has prompted analysts to raise their valuation expectations for the Indonesian energy producer.
MedcoEnergi reported first-half revenue of about $1.415 billion and EBITDA of $805 million, according to its 2026 financial disclosures. Oil and gas production reached roughly 170.1 thousand barrels of oil equivalent per day, up about 19% from the same period a year earlier.
The earnings increase was particularly sharp compared with the first half of 2025. Net income attributable to shareholders rose almost eightfold to about $275.3 million from roughly $30.7 million, according to the company’s first-half results.
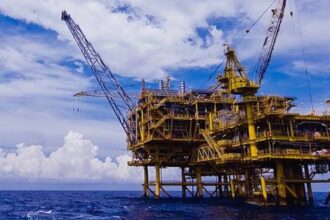
The company has maintained its 2026 production guidance at 165,000 to 170,000 barrels of oil equivalent per day. First-half production at around 170,000 barrels a day puts Medco near the upper end of that range.
MedcoEnergi is also continuing to invest in upstream development. Its 2026 oil and gas capital expenditure guidance stands at about $450 million to $475 million, while the company continues to advance projects including the Sakakemang gas development.
Sakakemang remains one of the key developments in Medco’s domestic gas portfolio. The company has targeted first gas from the project in the third quarter of 2027, adding a potential source of production growth beyond the current year.
The company has also strengthened its domestic gas position through commercialization agreements covering Sakakemang and Corridor gas. Those agreements are part of Medco’s strategy to connect its upstream resources with growing demand for natural gas in Indonesia.
Medco’s portfolio is increasingly diversified across oil and gas, power generation and mining. In the first quarter, power generation reached 1,053 GWh, up 20.8% year on year, while oil and gas production increased 18.1%, showing the contribution of multiple operating segments to group performance.
The market has responded to the stronger operating outlook. BRI Danareksa recently raised its target price for MedcoEnergi to Rp2,300 from Rp2,200 while retaining a Buy rating, citing expectations for production of 170 mboepd in 2026, 178 mboepd in 2027 and 179 mboepd in 2028.
The immediate focus for MedcoEnergi is therefore execution rather than a change in strategy. Sustaining production near the upper end of guidance, controlling costs and bringing new gas projects online will determine whether the sharp improvement in first-half earnings can translate into another year of stronger cash generation and production growth.
INSIGHT :
- 01
- 02
- 03
- 04
- 05
- 06