
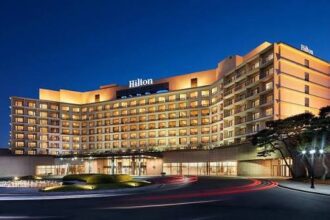
(New York) — Hilton Worldwide Holdings Inc. reported net income of $865 million in the first half of 2026, up 16.6% from $742 million a year earlier. The global hospitality group, listed on the New York Stock Exchange under the ticker HLT, generated revenue of $6.28 billion, an increase of 7.6% from $5.83 billion in the same period last year. Growth was supported by higher franchise fees, management fees and the continued expansion of its global hotel network.
The results highlight the strength of Hilton’s business model, which relies on brands, management contracts, franchising and a global reservation platform. The company’s portfolio spans 28 brands and more than 9,400 properties, with nearly 1.4 million rooms across 144 countries and territories. Much of its expansion is carried out with third-party property owners, allowing Hilton to grow its network without bearing the full cost of hotel development.
In the second quarter of 2026, Hilton reported net income of $482 million, up from $442 million a year earlier. Adjusted EBITDA rose to $1.054 billion from $1.008 billion, while diluted earnings per share reached $2.10. Adjusted diluted earnings per share, excluding special items, came to $2.29, reflecting improved profitability amid continued growth in hotel activity.
Hilton’s consolidated revenue reached $3.34 billion in the second quarter, compared with $3.14 billion in the same period last year. The figure includes reimbursements for operating costs charged to hotel owners and recorded alongside the corresponding expenses. Investors therefore need to distinguish consolidated revenue from the fees and other income that more directly reflect the economics of Hilton’s franchise, management and ownership businesses.
One of Hilton’s key performance indicators is revenue per available room, or RevPAR, which measures room revenue relative to the number of rooms available. System-wide comparable RevPAR increased 3.9% in the second quarter of 2026 on a currency-neutral basis. Improvements in both occupancy and average daily room rates contributed to the increase.
Revenue from franchise and licensing fees reached $808 million in the second quarter, up from $745 million a year earlier. Overall management and franchise fee revenue increased 6.4% during the quarter and 8.3% in the first half. The figures demonstrate the economic value of Hilton’s brand network, as additional properties and higher booking activity can generate recurring fee income without requiring the company to own every hotel building.
Hilton opened 207 hotels with a total of 24,100 rooms during the second quarter of 2026. After accounting for rooms removed from the network, the company recorded 21,600 net room additions. Net unit growth reached 6.1% from June 2025, strengthening Hilton’s position as it competes for new hotel management and franchise agreements.
Hilton’s development pipeline reached a record 541,300 rooms across 3,853 hotels in 132 countries and territories as of June 30, 2026. The pipeline grew 6% from a year earlier, with 42,900 new rooms approved for development during the second quarter. More than half of the planned rooms were outside the United States, while nearly half were already under construction.
Hilton’s expansion strategy relies on a relatively asset-light business model. In many projects, third-party owners fund construction, renovations and property maintenance, while Hilton provides the brand, reservation systems, operating standards, loyalty programmes and management services under contractual arrangements. This approach allows the company to expand its global footprint and increase fee-based revenue without assuming the full financial risks associated with hotel ownership.
In June 2026, Hilton launched Undergraduate by Hilton, a new upper-midscale brand targeting hotels near colleges and universities. The brand is designed to serve education-related travel, family visits, campus events and business trips connected to academic institutions. Hilton sees potential for more than 400 hotels in the market segment targeted by the brand.
The launch adds to Hilton’s efforts to broaden its portfolio across price points and travel categories. Earlier in 2026, the company introduced Apartment Collection by Hilton, designed to bring apartment-style accommodation into its branded network. The first three properties under the collection began operating during the second quarter in Salt Lake City, Austin and Atlanta.
Hilton is also expanding its luxury and lifestyle portfolio through new projects and brand agreements. During the second quarter, the company signed agreements for Waldorf Astoria Miami Beach and Umfolozi River Hotel in South Africa, which will join Tapestry Collection by Hilton. In Europe, Conrad Athens The Ilisian marked the Conrad brand’s arrival in Greece, while Slohh by Roach Bengaluru expanded Curio Collection by Hilton in India.
The company’s 2026 development activity also includes new properties and a stronger presence in several regional markets. Hilton has announced projects or openings across Malaysia, Saudi Arabia, Singapore, India, Thailand, Italy, Ireland and Fiji through different brands in its portfolio. NoMad Hilton Singapore is among the projects attracting attention as the NoMad brand expands into Asia-Pacific.
In Asia-Pacific, Hilton’s system-wide comparable RevPAR rose 1.2% in the second quarter of 2026 from a year earlier on a currency-neutral basis. Regional occupancy reached 68.6%, while the average daily room rate was $97.42. The performance was more moderate than in the United States, where RevPAR increased 5.4%, highlighting the different demand and pricing dynamics across Hilton’s markets.
Hilton strengthened its financing capacity in May 2026 by issuing $1 billion of senior notes carrying a 5.5% coupon and maturing in 2031. Part of the proceeds was used to repay $450 million previously drawn under the company’s revolving credit facility. The transaction helped manage the debt structure while preserving financing flexibility for corporate requirements.
As of June 30, 2026, Hilton had approximately $13.4 billion in outstanding debt, with a weighted average interest rate of 5.03%. The company also held $1.064 billion in cash and cash equivalents, alongside available borrowing capacity under its revolving credit facility. Hilton said it had no material debt maturities until April 2029, apart from $600 million of notes due in April 2027.
Capital returns remain a major part of Hilton’s financial strategy. During the second quarter of 2026, the company repurchased 2.9 million shares for approximately $932 million. Share repurchases for the first half totalled 5.6 million shares, while total capital returned to shareholders, including dividends, reached approximately $1.83 billion during the first half and $2.03 billion through July.
Hilton maintained its quarterly cash dividend at $0.15 per share. Dividend payments during the first half totalled $69 million, while management projected total capital returns to shareholders of approximately $3.5 billion for 2026. The combination of dividends and share repurchases forms part of Hilton’s capital allocation policy as it continues to expand its global network.
Management raised its full-year outlook following a strong first-quarter performance and continued momentum in the second quarter. For 2026, Hilton expects system-wide comparable RevPAR to increase by 3% to 3.5%, with net income projected at $1.883 billion to $1.911 billion. Adjusted EBITDA is forecast to reach $4.04 billion to $4.08 billion, while net unit growth is expected to range from 6% to 7%.
The outlook depends on sustained travel demand, room pricing and Hilton’s ability to bring new properties into its network on schedule. Management expects third-quarter RevPAR to increase by about 4% from the same period in 2025, supported in part by calendar effects and travel activity associated with the FIFA World Cup. Macroeconomic uncertainty, inflation, interest rates, labour costs and geopolitical tensions remain risks for the global hospitality industry.
Beyond organic expansion, Hilton is relying on brand development, owner relationships and its loyalty programme to strengthen its competitive position. Hilton Honors has more than 260 million members, providing a substantial base for direct bookings, customer retention and cross-brand spending. The company is also expanding digital services, including digital room keys and booking features, to improve the guest experience and strengthen its direct distribution channels.
INSIGHT :
- 01
- 02
- 03
- 04
- 05
- 06